Banks Face New 'Know Your Agent' Rules as AI Handles Payments
Financial institutions are building compliance frameworks to verify autonomous AI agents that could orchestrate $5 trillion in spending by 2030.
Financial institutions are confronting a fundamental shift in transaction compliance as AI agents gain the ability to initiate payments and execute financial tasks autonomously. The industry's established "know your customer" protocols were designed for human actors—not software that can make decisions on behalf of users.
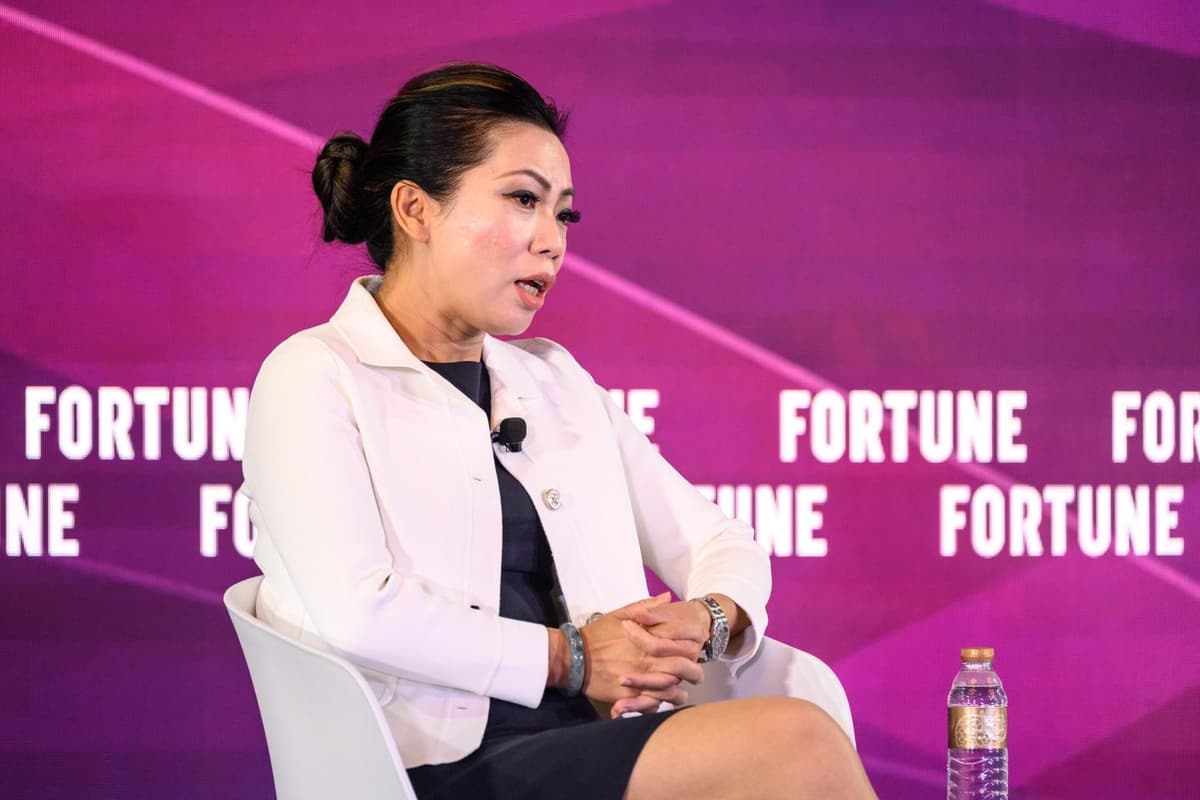
Zhuoqun Bian, president of Ant Digital Technologies, outlined the challenge at the Fortune Leaders Forum in Macau in early September. When AI agents conduct transactions, banks need to verify not just the customer but the agent itself: who built it, who authorized it, and who bears responsibility when something goes wrong.
McKinsey projects that AI agents could orchestrate up to $5 trillion in global consumer spending by 2030, according to research published in January. Yet payment infrastructure—from card networks to settlement systems—was built on the assumption of predictable human behavior and clear legal accountability.
Industry Moves to Build Standards
Ant International, the global payments division of Ant Group, announced in early September that it is collaborating with Mastercard and Visa on an interoperability framework for agent verification. The initiative aims to enable card networks, digital wallets, and marketplaces to recognize and authenticate trusted AI agents across different platforms.
The work is being coordinated through BuildFin.ai, an industry platform convened by the Monetary Authority of Singapore. The goal is to create standards that allow agents to operate across financial ecosystems while maintaining the security and compliance requirements banks are legally obligated to uphold.
The Technical Challenge
The International Monetary Fund highlighted a core tension in an April analysis: AI agents are probabilistic and adaptive, meaning they can produce different outputs from identical inputs. Payment systems, by contrast, must be deterministic—the same transaction must always produce the same result to maintain trust and financial stability.
Benson Wong, managing director and head of digital at JPMorgan Private Bank, pointed to operational risk rather than technical failure as the primary concern. In his experience, problems arise not from agent technology itself but from inadequate processes, controls, and compliance frameworks around how agents are deployed.
The stakes scale with autonomy. An agent that provides incorrect information creates an awkward moment; an agent that executes the wrong financial transaction can have cascading consequences across systems and accounts.
Why It Matters
As AI agents move from answering questions to initiating payments and managing accounts, banks face regulatory exposure without clear precedent. Traditional KYC rules assign liability to identifiable humans. When an agent acts on ambiguous instructions or makes probabilistic decisions with financial consequences, existing compliance frameworks may not clearly establish who is responsible. Building "know your agent" standards now could prevent a regulatory crisis as agent adoption accelerates—but only if the industry can agree on verification methods before agents become deeply embedded in payment flows.
Bian emphasized the urgency: "You need to know your agents much more than you know your customers." The infrastructure that supports agent-driven transactions will need to be rebuilt or fundamentally enhanced to accommodate this new category of actor in the financial system.
These details were first reported by Fortune.
This is an original analysis by the Omega editorial team. Source reporting: AI Watch.
Want systems like this working for your business?
Book a Call